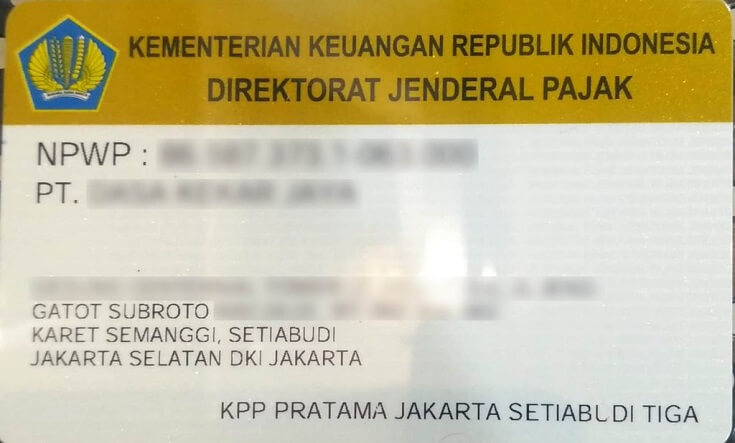
NPWP stands for Nomor Pokok Wajib Pajak, Indonesia’s taxpayer identification number. In English, it is commonly called a tax identification number or TIN. The Directorate General of Taxes (DJP) uses NPWP to identify taxpayers and administer their tax rights and obligations.
Key Takeaways
- NPWP means Nomor Pokok Wajib Pajak. It identifies individuals and entities in Indonesia’s tax administration system.
- Indonesia uses a 16-digit NPWP framework. For registered individual taxpayers classified as residents under population-administration rules, the standard identifier is an activated NIK. A transition rule covers certain existing records whose NIK data has not yet been matched.
- Companies and individuals outside the resident population-administration category use DJP-issued 16-digit identifiers when registered as taxpayers.
- An Indonesian company’s NPWP belongs to the company. Its founder or director may need a separate personal tax registration, depending on individual circumstances.
What Is an NPWP Used for in Indonesia?
An NPWP identifies the taxpayer connected to an Indonesian tax record. Article 3 of DJP Regulation PER-7/PJ/2025 describes its use in administering tax rights and obligations.
Depending on the taxpayer’s circumstances, DJP uses NPWP for income tax payments, withholding, reporting, refunds, and other tax services. Other institutions may also request the number when their procedures require taxpayer identification.
For example, an Indonesian company may need to provide its NPWP when preparing withholding tax documents or completing financial administration with another business.
An expatriate who receives income in Indonesia may encounter the same identifier in personal tax administration. The relevant number depends on the individual taxpayer’s registration status.
An NPWP identifies the taxpayer; it does not prove that any tax has been paid. VAT taxable-entrepreneur status, known as Pengusaha Kena Pajak or PKP, is a separate registration or confirmation matter and should be checked independently.
Why Does an Indonesian NPWP Have 16 Digits?
Indonesia’s tax identification framework uses 16-digit numbers. The familiar 15-digit NPWP format was replaced as part of the transition to the current tax administration system.
Article 2 of PER-7/PJ/2025 distinguishes the applicable identifier according to the taxpayer category.
| Taxpayer Category | NPWP Format | What to Check |
|---|---|---|
| Individual classified as a Penduduk under population-administration rules | Activated 16-digit NIK under the standard rule. A DJP-issued 16-digit identifier may apply to an existing unmatched record pending data correction. | Confirm that the individual’s NIK has been matched and activated as NPWP. |
| Individual outside the Penduduk category | DJP-issued 16-digit NPWP | Confirm the number assigned to the individual’s registered tax record. |
| Company or other registered corporate taxpayer | DJP-issued 16-digit NPWP | Use the identifier registered under the company’s legal name. |
PER-7/PJ/2025 also addresses existing resident-individual records whose identities were not matched when the regulation took effect.
Under Article 2(5), those taxpayers may have a DJP-issued 16-digit identifier. Article 2(6) requires them to update their data so DJP can activate the NIK as NPWP.
This transition rule concerns existing unmatched records. It should not be interpreted as a permanent alternative for every new resident-individual registration.
Two Different Meanings of Resident
Indonesia uses the term Penduduk in population administration and subjek pajak dalam negeri in income tax law. The first affects NPWP identification format. The second determines income-tax residency under separate rules. Having a NIK does not, by itself, settle your income-tax residency.
What Happens to an Older 15-Digit NPWP?
You may still find a 15-digit NPWP on an older company document or tax record. DJP’s February 2025 explanation of the transition describes how existing corporate and certain individual numbers moved to the 16-digit format.
For existing corporate taxpayers and individuals outside the Penduduk category, the conversion involved adding a leading zero to the previous 15-digit identifier.
For resident individuals, the standard identifier is the NIK activated as NPWP, subject to the transition exception described earlier.
Ask your accountant to verify the current number in DJP’s records before updating invoices, withholding documents, or company registration files. Avoid manually changing a number based on its length alone.
Notes from InvestinAsia Consultants
When reviewing a foreign-owned company’s tax documents, start with the registered taxpayer’s name. A founder’s NIK, an older corporate NPWP, and a current corporate NPWP can appear in the same document folder. Match each identifier to its taxpayer before transferring the details to a new form.
Who Needs an NPWP in Indonesia?
Tax registration depends on whether an individual or entity meets the applicable requirements. Article 2(1) of PER-7/PJ/2025 requires taxpayers who meet the subjective and objective conditions to register with DJP.
The rules distinguish individuals from corporate taxpayers. For foreign nationals, the person’s identification status and Indonesian tax position also need separate consideration.
Indonesian Individuals and Other NIK Holders
An individual classified as a Penduduk under Indonesian population-administration rules generally uses an activated NIK as NPWP when registered as a taxpayer.
Under PER-7/PJ/2025, the Penduduk category can include Indonesian citizens and foreign nationals who reside in Indonesia under the applicable population-administration rules.
Nationality alone does not determine which tax identification format applies.
Possessing a NIK also does not automatically create an income-tax payment obligation. DJP has addressed this distinction in its explanation of NIK integration with NPWP.
Similarly, reaching the age of 17 does not automatically establish a universal obligation to register for a separate individual NPWP. DJP considers the applicable registration requirements and the person’s circumstances.
Foreign Individuals Living or Working in Indonesia
Foreign nationals may need individual tax registration when their circumstances meet Indonesian tax requirements. Residence, employment, business activities, and income can affect the assessment.
For income-tax residency, PER-23/PJ/2025 identifies several possible routes to Indonesian resident status.
Articles 3 and 4 cover individuals who live in Indonesia, spend more than 183 days in Indonesia within a 12-month period, or are present during a tax year with an intention to reside.
DJP also recognizes relevant evidence of an intention to reside. Depending on the facts, this may include a KITAP, certain long-term VITAS or ITAS permits, or employment and housing documents.
The 183-day test is not a mandatory waiting period before Indonesian tax consequences can arise. A person may satisfy another residency criterion sooner.
Indonesian-source income may also have tax consequences for someone who remains a non-resident for income-tax purposes.
Tax residency, personal NPWP registration, and the tax treatment of Indonesian-source income are related questions. Each requires its own assessment.
For foreign applicants, the identification format follows their population-administration category and registered taxpayer status. PER-7/PJ/2025 provides a DJP-issued 16-digit identifier for registered individuals outside the Penduduk category.
A foreign national classified as a Penduduk generally follows the activated-NIK framework, subject to the regulation’s unmatched-record provisions.
Also Read: Do Foreign Individuals in Indonesia Need an NPWP to Use Coretax?
Indonesian Companies, Including PT PMA
An Indonesian company has a tax identity registered under its own legal name. The company’s NPWP remains separate from its shareholders’ and directors’ personal identifiers.
This distinction applies to foreign-owned limited liability companies, commonly called PT PMA.
Under Article 12(1)(c) of PER-7/PJ/2025, a corporate taxpayer must register no later than one month after it is established or becomes domiciled in Indonesia.
The corporate registration deadline is separate from business licensing requirements and the registration of additional business locations.
DJP’s corporate registration guidance identifies establishment documents among the supporting materials for domestic corporate taxpayers. Requirements may differ for other entity categories.
For the company-specific process, read our guide to NPWP registration for PT PMA companies in Indonesia.
Personal NPWP Versus Company NPWP: A Foreign Founder’s Example
Consider a Singapore-based founder who establishes an Indonesian PT PMA while continuing to live in Singapore.
The Indonesian company must establish its own tax identity. The founder’s individual tax position requires a separate assessment based on the person’s residence, income, and activities.
The company’s NPWP cannot replace the founder’s personal tax identifier when an individual identifier is required.
Now suppose the founder relocates to Indonesia and obtains an Indonesian NIK after registering for an individual NPWP outside the Penduduk category.
Article 2(7) of PER-7/PJ/2025 requires a taxpayer in that situation to update the existing DJP-issued identifier to the activated NIK.
The change concerns the founder’s individual tax record. The PT PMA retains its separate corporate NPWP.
Foreign founders should keep these records distinct when preparing employment documents, tax filings, and corporate administration.
Notes from InvestinAsia Consultants
Before preparing a foreign founder’s personal tax registration, distinguish the founder’s activities from the PT PMA’s activities. Review who receives the income, who is party to the contract, who bears the obligations, and which taxpayer must report the transaction. These facts help identify the relevant record, although they do not replace a full tax assessment.
NPWP, NIK, NIB, and NITKU: Which Number Do You Need?
Foreign founders often encounter several Indonesian identification numbers during company registration. Each number belongs to a particular administrative system or serves a particular tax function.
| Identifier | Meaning | Main Purpose |
|---|---|---|
| NPWP | Nomor Pokok Wajib Pajak | Identifies a taxpayer in DJP’s tax administration system. |
| NIK | Nomor Induk Kependudukan | Identifies an individual in population administration. An activated NIK serves as NPWP for the relevant individual taxpayer category. |
| NIB | Nomor Induk Berusaha | Serves as evidence of business registration and identifies the business actor in Indonesia’s OSS business-licensing system. It is not a substitute for NPWP. |
| NITKU | Nomor Identitas Tempat Kegiatan Usaha | Identifies registered business locations, including the principal location and additional locations, for location-specific tax administration. |
Why NITKU Matters for Companies With Multiple Locations
NITKU identifies business locations under a taxpayer’s central NPWP. DJP also assigns NITKU to a taxpayer’s residence or registered seat when the taxpayer registers.
Under Articles 31 to 33 of PER-7/PJ/2025, taxpayers must report their business locations. They must report a new business location no later than one month after establishing it.
DJP uses NITKU for location-specific administration. Depending on the transaction, this can include branch staff access, employee work-location reporting, and tax-invoice address data.
For a PT PMA with a Jakarta head office and operations in another city, the finance team should confirm that DJP has recorded the relevant locations.
NITKU is a location identifier within the taxpayer’s records. The company continues to use its registered corporate NPWP.
For business licensing, Government Regulation No. 28 of 2025 provides the risk-based licensing framework in which NIB functions as a business identifier. Additional licensing requirements may apply according to the business activity.
Also Read: Business Registration Number vs Tax ID: The Key Differences
How to Check or Register an NPWP Through Coretax
Before opening Coretax DJP, identify what you need to do. A person who already has an NPWP may need account access or a data update. A new taxpayer may need registration.
DJP’s Coretaxpedia guidance distinguishes three situations.
1. You Need Taxpayer Registration or NIK Activation
Use the applicable taxpayer-registration procedure when the individual or company meets Indonesia’s registration requirements and has not completed the relevant registration.
For a resident individual with a NIK, this may involve activating the NIK as NPWP through the individual registration process.
2. You Already Have an NPWP but Need Coretax Access
Existing taxpayers should check their current tax record before attempting another registration.
DJP provides different access arrangements for taxpayers who previously used DJP Online and those who already have an NPWP but never created a DJP Online account.
According to Coretaxpedia’s guidance updated on April 14, 2026, eligible former DJP Online users can follow the password-reset process to access Coretax.
Its separate guidance for registered taxpayers without a DJP Online account explains the taxpayer-account activation process.
3. You Need Coretax Access Without Active Taxpayer Registration
DJP provides a menu called Hanya Registrasi, meaning Registration Only, for certain people who need Coretax access without first registering as active taxpayers.
Coretaxpedia identifies examples involving certain tax payments and individuals appointed to act on behalf of another taxpayer.
The applicable procedure depends on the person’s status and purpose for accessing the system.
Having a Coretax account does not, by itself, establish that someone’s NIK has been activated as NPWP or that a particular tax payment is due.
How to Get an NPWP in Indonesia
DJP provides taxpayer registration through its official administrative channels, including Coretax DJP. The required procedure and supporting documents depend on the applicant category.
Registering as an Individual
DJP’s Coretaxpedia guidance for new resident-individual registration, last updated September 17, 2025, describes an online process for applicants with a NIK.
The published procedure includes selecting individual registration, choosing NIK activation, and completing the requested identity and contact details.
The applicant verifies contact information through a one-time password and completes identity verification using a selfie.
Under that guidance, successful applicants receive their NPWP information and digital NPWP document in PDF format through the registered email address.
Follow the requirements displayed in Coretax when applying. DJP may update its procedures and verification steps.
Foreign applicants without a NIK should use the registration route applicable to their identification and population-administration status.
DJP provides different access arrangements for foreign applicants and individuals outside the resident population-administration category. Contact the relevant KPP if your identification or verification status needs clarification.
Registering an Indonesian Company
A company registers using its legal identity and the supporting documents required for its taxpayer category.
Article 14(5) of PER-7/PJ/2025 addresses supporting documentation for corporate taxpayer registration. DJP’s registration guidance also identifies establishment documents as relevant evidence for domestic companies.
For a PT PMA, confirm that the company’s registered name and establishment details match the information provided to DJP.
Foreign representative offices and permanent establishments may need different supporting documentation. The requirements should follow the applicable entity category.
DJP does not charge a fee for its official NPWP registration service. A private adviser may charge separately for document preparation, coordination, or ongoing tax work.
Confirm the scope and professional fees before engaging a service provider.
What to Do After Receiving Your NPWP
Once DJP confirms your registration, keep the current tax identifier with the correct taxpayer’s records.
For a company, the finance team should verify the corporate NPWP, registered legal name, and relevant business locations before preparing tax documents.
Founders and directors should maintain their personal records separately, especially when they relocate to Indonesia or take on new roles.
Registration also brings the need to assess the taxpayer’s ongoing obligations. The applicable filings and payments depend on the taxpayer’s activities, income, and tax status.
Our article on PT PMA tax obligations in Indonesia explains the corporate compliance questions that follow company registration.
For foreign founders who need their company registration and tax records reviewed together, InvestinAsia’s tax compliance service provides a route to discuss registration and related tax administration needs.
InvestinAsia is a private corporate-services provider and part of vOffice Group. Confirm the engagement scope and professional fees directly with the team before proceeding.
Need to Check Your Personal or Company NPWP?
Discuss Indonesian tax registration and compliance needs with InvestinAsia, backed by vOffice Group.
- Direktorat Jenderal Pajak. (2025). Peraturan Direktur Jenderal Pajak Nomor PER-7/PJ/2025 tentang Petunjuk Pelaksanaan Administrasi Nomor Pokok Wajib Pajak, Pengusaha Kena Pajak, Objek Pajak Pajak Bumi dan Bangunan serta Perincian Jenis, Dokumen, dan Saluran untuk Pelaksanaan Hak dan Pemenuhan Kewajiban Perpajakan. Retrieved from
https://pajak.go.id/id/peraturan/petunjuk-pelaksanaan-administrasi-nomor-pokok-wajib-pajak-pengusaha-kena-pajak-objek - Kementerian Keuangan Republik Indonesia. (2025). PER-7/PJ/2025: Official legal-document record. Retrieved from
https://jdih.kemenkeu.go.id/dok/per-7pj2025 - Direktorat Jenderal Pajak. (2025). Peraturan Direktur Jenderal Pajak Nomor PER-23/PJ/2025 tentang Penentuan Subjek Pajak Dalam Negeri dan Subjek Pajak Luar Negeri. Retrieved from
https://www.pajak.go.id/id/peraturan/penentuan-subjek-pajak-dalam-negeri-dan-subjek-pajak-luar-negeri-0 - Direktorat Jenderal Pajak. (2025, February 28). Coretax DJP, Era NPWP 16 Digit. Retrieved from
https://pajak.go.id/id/artikel/coretax-djp-era-npwp-16-digit - Direktorat Jenderal Pajak. (2025, September 17). Coretaxpedia: Pendaftaran WP Orang Pribadi. Retrieved from
https://pajak.go.id/coretaxpedia/pendaftaran-wp-orang-pribadi - Direktorat Jenderal Pajak. (2026, April 14). Coretaxpedia: Akses Coretax bagi User DJP Online. Retrieved from
https://www.pajak.go.id/coretaxpedia/akses-coretax-bagi-user-djp-online - Direktorat Jenderal Pajak. (2026, January 19). Coretaxpedia: Akses Coretax bagi Bukan User DJP Online. Retrieved from
https://www.pajak.go.id/coretaxpedia/akses-coretax-bagi-bukan-user-djp-online - Direktorat Jenderal Pajak. (2025, November 27). Coretaxpedia: Menu Hanya Registrasi. Retrieved from
https://www.pajak.go.id/coretaxpedia/menu-hanya-registrasi - Direktorat Jenderal Pajak. (n.d.). Pendaftaran Wajib Pajak Badan. Retrieved from
https://pajak.go.id/panduan-layanan-pajak/konten/registrasi/pendaftaran-wajib-pajak/pendaftaran-wajib-pajak-badan - Direktorat Jenderal Pajak. (2021, October 14). NIK Sebagai NPWP, Belum Tentu Bayar Pajak. Retrieved from
https://www.pajak.go.id/id/artikel/nik-sebagai-npwp-belum-tentu-bayar-pajak - Direktorat Jenderal Pajak. (2024, July 16). Mengenal NITKU, Pengganti NPWP Cabang? Retrieved from
https://www.pajak.go.id/id/artikel/mengenal-nitku-pengganti-npwp-cabang - Kementerian Investasi dan Hilirisasi/BKPM. (2025). Peraturan Pemerintah Nomor 28 Tahun 2025 tentang Penyelenggaraan Perizinan Berusaha Berbasis Risiko. Retrieved from
https://jdih.bkpm.go.id/id/document/peraturan-pemerintah-nomor-28-tahun-2025-tentang-penyelenggaraan-perizinan-berusaha-berbasis-risiko - Direktorat Jenderal Pajak. (n.d.). Buka di MPP, KPP Sukoharjo Berikan Layanan Perpajakan. Retrieved from
https://pajak.go.id/id/berita/buka-di-mpp-kpp-sukoharjo-berikan-layanan-perpajakan