
A PT PMA preparing its FY2026 corporate tax return should confirm who can access and sign in Coretax, review which monthly returns actually apply, reconcile tax documents with its accounts, and assemble its financial statements before filing in 2027. Foreign ownership alone does not make every monthly return, audited statement, or transfer pricing document mandatory.
Key Takeaways
- Check the company’s Coretax access, authorized user roles, and DJP authorization code before the filing window.
- Monthly reporting depends on the company’s tax status and transactions. A VAT-registered business must report its monthly VAT return even when the result is nil.
- For a calendar-year company, the normal deadline for the FY2026 corporate annual income tax return is 30 April 2027.
- Reconcile invoices, withholding records, payments, and financial statements before relying on figures shown in a Coretax draft.
Start With the Company’s Coretax Access
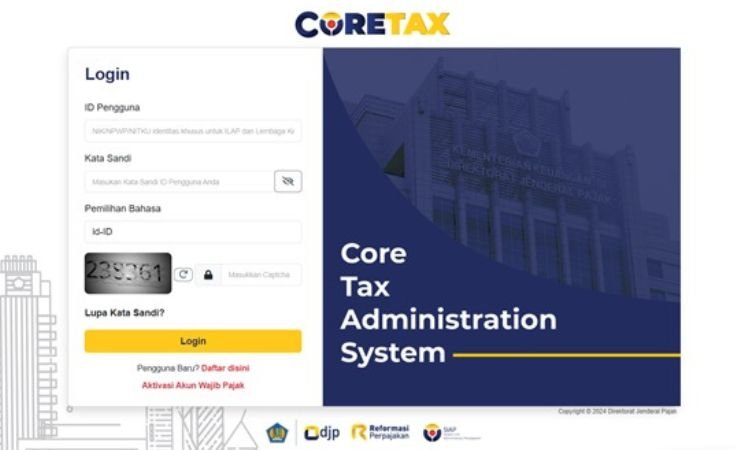
Coretax is the Directorate General of Taxes’ system for tax administration and reporting. For an established PT PMA, the first readiness check is whether the correct people can act for the company in the system. It is more useful than assuming a filed return can be completed simply because someone knows the company’s NPWP.
Confirm the company’s registered contact details, the person in charge (PIC), any delegated roles, and the DJP authorization code or electronic certificate needed for electronic signing. DJP’s Coretax guidance explains how an individual can view the taxpayers they represent and the roles assigned to them. Account activation and a request for a DJP authorization code have no separate fixed deadline, but they need to be completed before the relevant service is used.
- Record who prepares, reviews, signs, and submits each return.
- Check that the authorized person can access the company’s taxpayer account.
- Test access early enough to resolve an incorrect role or contact detail.
- Keep the authorization record separate from shared working files and passwords.
Map Monthly Returns to Actual Obligations
A PT PMA should maintain a monthly filing matrix based on its tax registrations and transactions. The claim that every foreign-owned company must submit every type of nil monthly return is too broad. Review payroll, supplier payments, non-resident payments, and VAT registration separately.
| Reporting Area | Readiness Check | Evidence to Retain |
|---|---|---|
| Employee withholding | Review payroll and the applicable PPh 21/26 reporting position, including the December period. | Payroll register, withholding slips, payment records, and submitted return. |
| Other withholding | Identify payments that create withholding or collection obligations, including relevant domestic and cross-border payments. | Contracts, invoices, withholding slips, payment evidence, and recipient details. |
| VAT | Confirm whether the company is registered as a taxable entrepreneur (PKP). A PKP must submit its monthly VAT return even when it is nil. | Sales and purchase invoices, tax invoices, credits, payments, and return receipts. |
The Directorate General of Taxes expressly states that a PKP remains required to report a nil VAT return. It also identifies a December PPh 21 reporting obligation even where no employee income was paid in that period. These specific rules should guide the filing matrix; a blanket rule for all nil returns should not.
Reconcile Tax Credits Before Filing
Coretax data should be checked against the company’s own records. Match withholding slips received from customers, tax payments, VAT invoices, and any carried-forward balances to the general ledger and the relevant return period. Investigate missing or duplicate items before approving the annual calculation.
This check matters particularly when a return has been corrected. DJP’s September 2026 explanation of Regulation PER-12/PJ/2026 says Coretax updates compensation balances when a taxpayer corrects certain monthly PPh 21/26 or VAT returns. Keep the original return, correction, payment evidence, and resulting balance together so the FY2026 file shows which figure is current.
Notes from InvestinAsia Consultants
Assign an owner to each difference between the ledger and Coretax. A list that records the tax period, source document, amount, and resolution makes the final review more useful than a single year-end total.
Build the FY2026 Corporate Return File
For a company whose tax year ends on 31 December 2026, the normal deadline for its corporate annual income tax return is 30 April 2027. The Directorate General of Taxes states the general rule as four months after the tax year ends. A PT PMA with a different tax year must calculate its deadline from its own year-end.
Prepare the financial statements and tax reconciliation before opening the final return. DJP’s corporate Coretax guidance starts with the main form and then the applicable attachments; attachment details vary by business sector and the answers entered. An audited financial statement should be supplied where an audit applies to that company. An audit is not mandatory solely because the company is a PT PMA.
- Final trial balance, profit and loss statement, balance sheet, and supporting ledgers.
- Reconciliation from accounting profit to taxable income.
- Monthly return receipts, withholding slips, and tax payment evidence.
- Records supporting deductions, tax credits, and any applicable loss carryforward.
- Related-party agreements and transfer pricing support where the applicable rules require them.
- A review record showing who approved the figures and authorized submission.
Our guide to filing a corporate tax return in Coretax covers the submission steps. This checklist focuses on deciding whether the company’s records and access are ready for those steps.
Finding Gaps Between Your Tax Records and Coretax?
InvestinAsia offers tax compliance and reporting support, backed by 380+ specialists across the group.
Resolve Errors and Keep Proof of Submission
Do not treat a saved draft or payment as proof that an annual return was submitted. DJP’s corporate Coretax materials show a reported-return area and an electronic receipt. Save the final return and its electronic receipt in the FY2026 evidence file.
When a role, document, or amount prevents filing, note the exact message, affected tax period, and steps already taken. Check the relevant DJP guidance and contact the company’s tax office or official DJP support channel when the problem cannot be resolved internally. If the annual return cannot be completed by the normal deadline, review the official extension procedure before that deadline rather than assuming an extension applies automatically.
For companies handling several monthly returns and a year-end reconciliation, InvestinAsia Tax Compliance provides a route to review the reporting scope and coordinate the records needed for filing. Our PT PMA tax obligations guide explains the wider tax categories; it serves a different purpose from this Coretax readiness checklist.
Prepare the FY2026 Return With a Clear Review Trail
Review access, applicable returns, and supporting documents before the 2027 filing window.
- Directorate General of Taxes. (n.d.). Corporate annual tax return filing deadlines. Retrieved from
https://www.pajak.go.id/id/batas-waktu-lapor - Directorate General of Taxes. (2025). Coretax guidance for filing a corporate annual income tax return. Retrieved from
https://www.pajak.go.id/coretaxpedia/lapor-spt-tahunan-badan - Directorate General of Taxes. (2026). Guidance on Coretax account activation and DJP authorization codes. Retrieved from
https://www.pajak.go.id/id/artikel/jangan-panik-aktivasi-akun-coretax-tidak-ada-batas-waktu - Directorate General of Taxes. (n.d.). Guidance on checking assigned Coretax access roles. Retrieved from
https://www.pajak.go.id/coretaxpedia/cek-role-akses-yang-diberikan - Directorate General of Taxes. (2026). Guidance on reporting a nil monthly VAT return. Retrieved from
https://pajak.go.id/id/artikel/meski-spt-ppn-nihil-pkp-tetap-wajib-lapor - Directorate General of Taxes. (2026). Guidance on the December monthly PPh 21 return. Retrieved from
https://www.pajak.go.id/id/artikel/penting-lima-hal-yang-harus-diperhatikan-saat-lapor-spt-pph-pasal-21-masa-desember-2025 - Directorate General of Taxes. (2026). Explanation of PER-12/PJ/2026 and corrections to monthly returns. Retrieved from
https://www.pajak.go.id/id/artikel/goodbye-skema-delta-coretax-kini-terapkan-skema-replace-mulai-1-oktober-2026-12pj2026